

A homeowner in Bedok recently sat with two renovation quotations spread across the kitchen table, both for roughly the same scope of work, and a bank’s loan offer sitting unread in her inbox. She had enough saved to cover perhaps two-thirds of the total, and no clear sense of whether borrowing the rest was a sound decision or a commitment she would regret for the next few years. Many Singapore homeowners find themselves in exactly this position somewhere between collecting a key or signing a tenancy and actually starting work.
Renovation financing rarely gets the same attention as flooring samples or kitchen layouts, yet how a project is paid for shapes almost every other decision that follows, from the scope committed to upfront to how much flexibility remains if costs shift mid-project. Understanding the actual mechanics, rather than assumptions picked up from a friend’s experience, is a useful first step before signing anything.
Why Renovation Costs Catch Even Careful Homeowners Off Guard
Even meticulous planners tend to underestimate a renovation’s true cost, not because they are careless, but because early budgets are usually built around a wishlist instead of a finalised scope. A quotation obtained at the concept stage can shift once electrical rewiring, hacking, or an unexpected structural issue surfaces during the works. Add in appliances, furniture, and the small additions that inevitably come up once a space starts taking shape, and a project that looked comfortably affordable on paper can start to strain a household’s cash reserves.
What a Renovation Loan Actually Involves
A renovation loan is typically an unsecured personal loan that banks in Singapore offer specifically for home improvement work. It differs from a home loan or an HDB loan, both of which finance the purchase of the property itself, not what happens inside it afterwards. Once a flat or house is bought, financing the fit-out is treated as a separate exercise entirely.
Banks generally assess eligibility against monthly income and existing debt obligations, and many also ask to see the renovation contract or quotation before releasing funds. Loan quantums are commonly capped at a multiple of monthly income, and repayment tenures usually run from one to five years. Funds are often disbursed directly to the contractor in stages tied to project milestones, instead of being handed to the homeowner as a lump sum, which keeps the loan tied to work actually completed.
Homeowners who cannot qualify for a bank renovation loan sometimes turn to a licensed moneylender instead, and while these are legally regulated with capped interest rates, the cost of borrowing is almost always higher than a bank’s. Anyone considering this route should confirm the lender is on the Ministry of Law’s official register before signing anything, and treat a far higher quoted rate as a signal to revisit the project’s scope, not simply accept the extra cost.
Why CPF Savings Won’t Help With a Renovation
It is a common assumption that CPF savings can be tapped for renovation costs the same way they can for a flat’s down payment, but this is not the case.
The CPF Board states plainly that CPF savings cannot be used for renovation, improvement or repair work on a property, which means renovation costs, however they are financed, need to come from cash, whether that is savings or a loan. Factoring this in early avoids an unpleasant surprise midway through planning, when a homeowner realises their CPF balance offers no cushion for the fit-out itself.
Cash Savings or a Loan: What to Weigh Up
Choosing between paying outright and borrowing is rarely a simple arithmetic exercise, since the right answer depends on a household’s broader financial position, not just the interest rate on offer. A few questions tend to clarify the decision faster than hours of comparing loan packages.
- How much of your emergency savings a full cash payment would leave untouched
- Whether the loan’s monthly instalment fits comfortably alongside existing commitments such as a mortgage or car loan
- How the interest cost over the full tenure compares with what those savings could otherwise earn or avoid in fees
- Whether staging the renovation in phases could reduce the amount that needs financing at all
- How confident you are in the quotation’s accuracy, since borrowing against an estimate that later balloons leaves far less room to manoeuvre
Protecting the Money You Borrow
Whichever way a renovation is funded, the greatest financial risk rarely comes from the financing itself. It comes from an unclear scope, vague verbal promises, or a contractor who disappears mid-project after receiving a large upfront deposit. Working with a firm accredited under the Consumers Association of Singapore’s CaseTrust scheme for renovation businesses offers some reassurance here, since accredited firms are required to meet set standards around contracts, deposits, and dispute handling.
A transparent, itemised quotation does more for a borrower than it might first appear. It lets you see exactly where every borrowed dollar is going, instead of trusting a single bottom-line figure, and it gives a named project manager something concrete to be held accountable against if costs start to drift from what was agreed. A twelve-month workmanship warranty, set out clearly from the start, carries extra weight when a loan’s repayment schedule stretches well beyond the handover date, since any defect that surfaces later should not become a fresh, unbudgeted expense.
A Simple Way to Budget Before You Apply
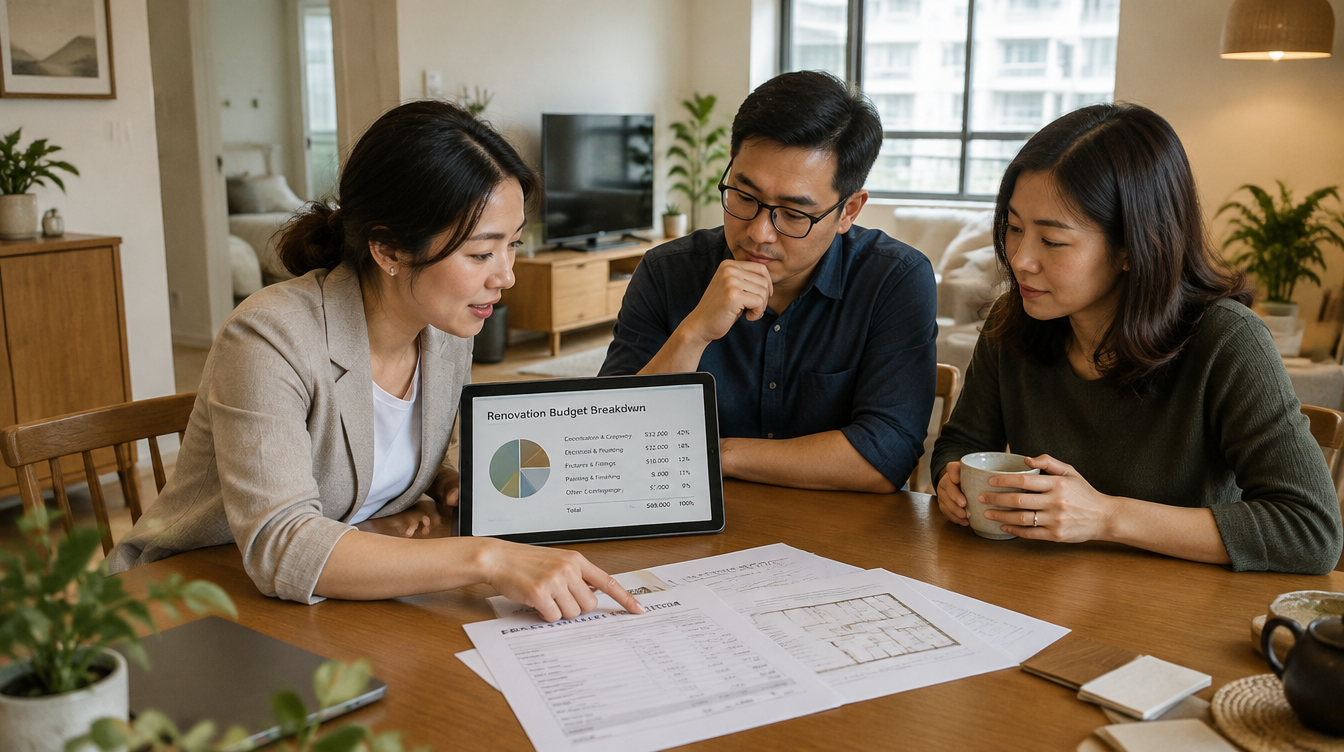
Before approaching any bank, it helps to build a realistic budget from the ground up, instead of working backwards from how much you think you can borrow. Start with firm quotations from at least two contractors, each broken down by trade instead of presented as a single number.
Add a contingency of around ten to fifteen per cent for the unexpected items that surface once the work is under way, since very few projects in Singapore finish without at least one. Set aside separately for furniture, appliances, and styling, since these are often excluded from a renovation quotation and tend to be underestimated badly when lumped in with everything else. Only once this fuller picture is in hand does it make sense to decide how much, if any, should be borrowed.
Homeowners who want to trim the total before deciding on financing at all might look into smart ways to save money on their renovation, many of which reduce the amount that needs borrowing without reducing the quality of the finished space. Paying for a renovation is rarely the most exciting part of a project, but treating it with the same care as the design itself tends to save both money and stress later on. If you are weighing up a loan against cash savings, or simply want a clearer sense of what your project should realistically cost, our team is happy to talk it through. Feel free to get in touch for a complimentary initial consultation.